Check Your Eligibility
Complete a short online application so your circumstances can be assessed and you can understand the finance options available before moving forward.
See exactly how it works, step by step. The Halal way.
Halal car finance lets you fund a car without paying or receiving interest. It uses a Shariah-compliant lease-to-own structure, Ijara wa Iqtina, tied to a real vehicle, with a clear route to owning it.
No interest is paid. You pay an agreed rental-profit charge. For easy comparison, we also show an APR-equivalent (annualised total charges). Rates from 7.9% APR-equivalent. Representative APR-equivalent 10.9%. Finance is subject to status.
Halal car finance gives you an Islamic alternative to conventional interest-based borrowing. The finance is structured around a real vehicle with clear, Shariah-compliant terms.
From the beginning, you can understand how the arrangement works, what you will pay and the agreed route towards owning your vehicle.
Five clear stages take you from your first eligibility check to the final ownership stage, with the finance structured around Islamic principles throughout.
Complete a short online application so your circumstances can be assessed and you can understand the finance options available before moving forward.
Choose a suitable vehicle from a trusted dealership. The finance arrangement is connected to the actual vehicle rather than being a conventional unsecured cash loan.
The finance is arranged using clear, Sharia-compliant terms. Your payment structure, responsibilities and route towards ownership are set out before you proceed.
Once everything is completed, you collect your vehicle and make the payments set out in your agreement throughout the agreed finance term.
Once the agreed finance journey is completed, the final ownership stage takes place in accordance with the terms set out in your finance agreement.
A Shariah-compliant route to owning your car. You use the vehicle through an agreed Ijara arrangement, then ownership transfers to you through Iqtina at the agreed completion point.
Ijara covers the agreed use of the vehicle during the finance term. Iqtina is the agreed transfer of ownership at completion.
The vehicle you choose is purchased and made available to you under an agreed rental arrangement. You use the car during the term while the finance provider remains the owner throughout the Ijara stage.
You use the vehicle throughout the agreed Ijara period.
At the agreed completion point, ownership of the vehicle transfers to you through Iqtina. The route to this transfer is established as part of the agreement from the outset.
You progress through the agreed Ijara term. Ownership transfers at the agreed completion point through Iqtina.
You choose the vehicle and the agreement is structured around that specific car. The agreed rental and term are confirmed before the arrangement begins.
You continue using the car under the agreed rental arrangement while the finance provider remains the legal owner of the vehicle during this stage.
The final part of the Ijara term is completed under the arrangement already agreed at the outset, bringing the agreement towards the Iqtina transfer stage.
Once the agreed term has been completed, ownership of the vehicle transfers to you through the agreed Iqtina arrangement. The car becomes yours.
There is no interest at any stage. You pay an agreed rental-profit charge for using a real vehicle, with the full cost set out clearly before you sign.
Instead of interest on money lent, you pay an agreed rental-profit charge to use the vehicle under the Ijara arrangement. For easy comparison, an APR-equivalent is also shown, which annualises the total charges so you can weigh it against conventional finance.
The APR-equivalent annualises the total charges so you can compare like for like. No interest is charged. Finance is subject to status.
Your payments are set and agreed before you sign, so you know the full cost from the start.
Any charges that apply are set out clearly in your agreement in advance, with nothing hidden.
You may be able to settle your agreement early if your circumstances change; the terms are confirmed in your agreement.
No interest is paid. You pay an agreed rental-profit charge. For easy comparison, we also show an APR-equivalent (annualised total charges). Rates from 7.9% APR-equivalent. Representative APR-equivalent 10.9%. Finance is subject to status.
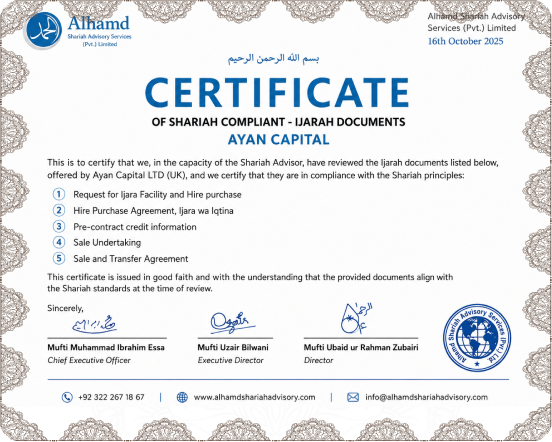
The Ijarah documents behind this finance structure have been independently reviewed by Alhamd Shariah Advisory, providing added confidence that the arrangement has been assessed against recognised Shariah principles.
Islamic finance is about more than changing terminology. The structure behind the transaction is what matters.
Throughout the Ijara period, the vehicle you choose is owned within the finance arrangement while you use it under agreed terms.
You pay an agreed rental for using the vehicle across the length of the Ijara term.
Each payment is the agreed rental for using the vehicle (the provider's profit) while you progress along the agreed path towards owning it.
At the agreed completion point, ownership of the vehicle transfers to you through Iqtina, as set out in the agreement.
This shows your progress through the agreed term. Ownership transfers at completion, not gradually each month.
At the end of the contract, a separate Sale and Transfer agreement is signed to legally transfer ownership of the vehicle to you. If you have met your Ijara obligations, there is nothing left to pay.
Applying for halal car finance doesn't need to feel complicated. We start with a few essentials about you, your driving status and your financial circumstances.
Keep these details to hand and you'll be better prepared to move through the eligibility process and onto choosing the right vehicle.
The questions people ask most about how halal car finance works, from how you pay to who owns the car and what happens at the end.
Halal car finance lets you fund a car without paying or receiving interest (riba). It uses a Shariah-compliant lease-to-own structure called Ijara wa Iqtina, where the finance is tied to a real vehicle. You use the car under an agreed rental during the term, and ownership transfers to you at the end.
No. Instead of interest on money lent, you pay an agreed rental-profit charge for using the vehicle under the Ijara arrangement. For easy comparison, we also show an APR-equivalent, which annualises the total charges. Finance is subject to status.
During the Ijara term, the finance provider owns the vehicle while you use it under an agreed rental. This ownership of a real asset is part of what makes the arrangement different from a conventional interest-based loan.
At the agreed completion point, ownership transfers to you through Iqtina. This is done through a separate Sale and Transfer agreement, and once your obligations under the agreement are met, there is nothing left to pay.
It is structured to avoid riba (interest) and gharar (unfair uncertainty), and it is tied to a real vehicle rather than a loan of money. The finance documents have been independently reviewed by Alhamd Shariah Advisory.
Under UK law, Ijara wa Iqtina is recognised as a form of hire purchase, which gives it consumer protection. The structure underneath is different: there is no interest and no unfair uncertainty, and the sale and transfer of ownership is a separate agreement.
No. The initial eligibility check uses a soft search, which does not affect your credit score. This lets you explore your options before deciding whether to make a full application.
Halal car finance is available to eligible applicants across the UK. You apply online, receive a decision, and choose a car from a trusted dealership, subject to status.
Yes. Halal car finance is open to everyone, whatever your faith. Many people choose it for the fixed, transparent structure, with no interest and clear costs agreed before you sign.
You may have the option to settle your agreement early if your circumstances change. The specific terms that apply are confirmed as part of your agreement, so it is worth discussing early settlement with us before you commit.
No. You arrange your own fully comprehensive insurance from the day you collect the car. Warranty is not included in the finance, though it may be possible to include it where it appears on the dealer invoice.
Not by design. You pay an agreed rental-profit charge instead of interest, with every cost fixed and disclosed before you sign. An APR-equivalent is shown so you can compare it like for like with conventional finance.
Now you know how it works, check your eligibility in minutes with a soft search. No riba, an agreed rental-profit charge, and a clear path towards owning your car. Open to everyone across the UK, whatever your faith.